Analysis of Uganda’s economy and the banking industry shows that:
- Deposits growth is strategically critical for financial institutions success. The cheaper the deposits, the more the competitiveness of the bank. Banks that lend more, get more deposits in return. As a financial institution executive, streamline your lending processes value chain and convenience, to ease loan access which tends to encourage customers to deposit more.
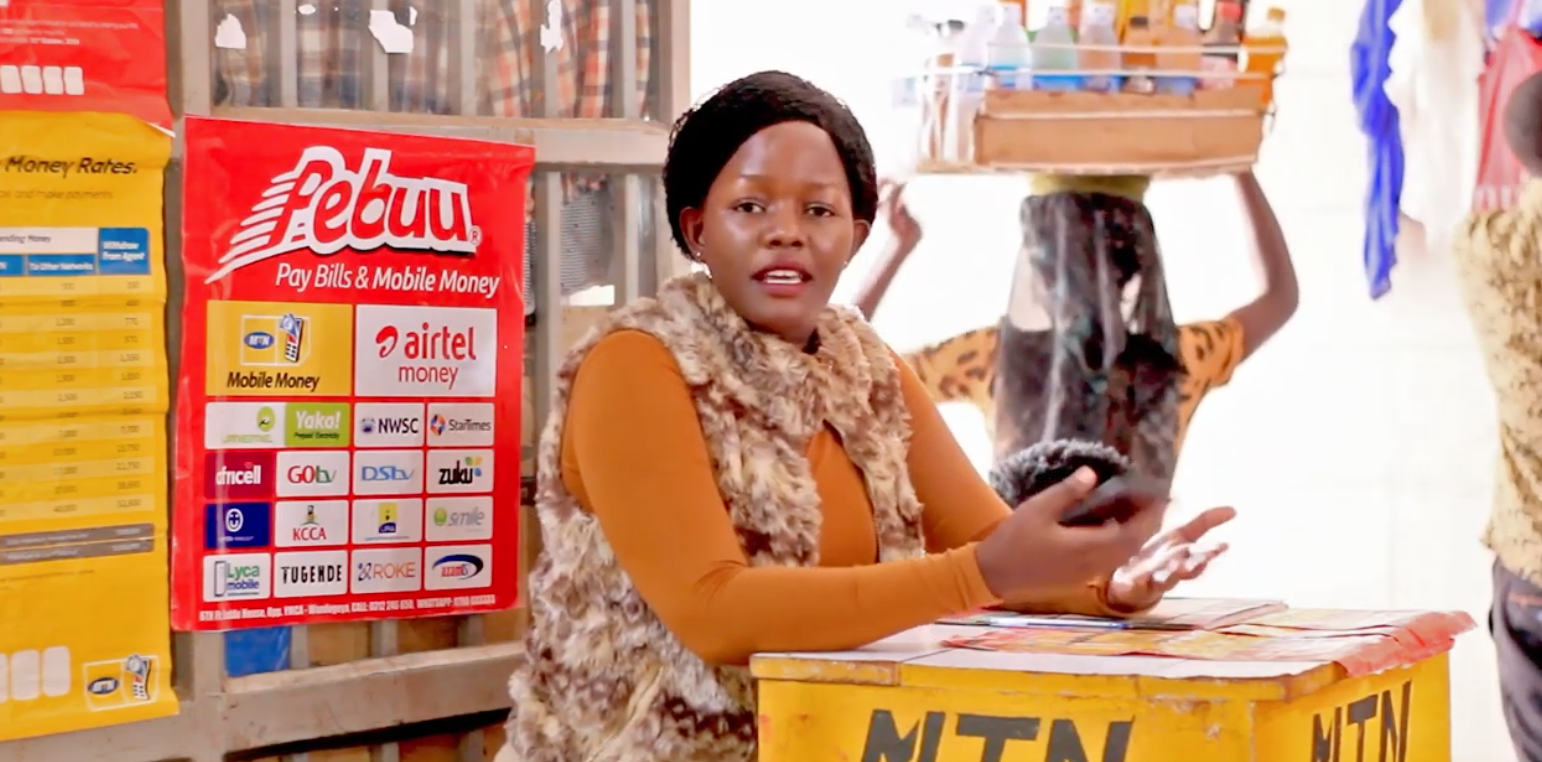
- Mobile money has driven deposits up, due to convenience. Some recipients of mobile money don’t withdraw all of it when they receive it. Those with bank accounts, transfer the money directly from the mobile to the bank account. Banks must therefore make the mobile to bank process seamless as a strategic imperative to win.
- Alternative channels take banking closer to the customers and thereby give convenience, are scalable and deliver a favourable jaws ratio (the rate at which revenue increases relative to the rate at which costs increase). Branches continue to be high-cost operations and we see winning banks further rationalizing their branch networks as boutique service centres, not as places customers go to line up and transact. To win, alternative channels must be integrated and not operated in silos.
- Winning banks build resilience within their portfolio through data analytics and business intelligence by lending to interconnected value chains within specific sectors. For example, banks were safer lending to cash crops and food crops industries in 2020 as these are economically resilient sectors. How are your credit systems identifying and lending to key players along critical value chains within a specific sector for a quality portfolio amidst tough times?
- A unit increase in the 90-Day T-bill yield by the Bank of Uganda tends to worsen non-performing loans to gross loans by 2.2 per cent as it triggers appetite for short term investments from banks that subsequently prefer to invest in fixed income rather than lend to the private sector which faces both default and liquidity risk.
- Convenient banking driven by digital developments like mobile, internet, agency banking and of course banking digital assistants like software on mobile gadgets for field staff will drive growth in the years to come and are of strategic imperative. Regardless of your clientele, now is the time to create a foundation for a shift to delivering convenient banking.
- Loans and advances continue to be the biggest boost of return on equity with an increased lending coefficient growing year on year return on equity by 30.45 per cent in boom years and low growth in recessions. The more quality loans you give out, the more you grow earnings. Creating deep customer relationships at origination is strategically critical.
- The directive from the Bank of Uganda to restructure loans and increase the interest rate on the bond and short-term interest rates have boosted earnings for banks as they have shifted the burden to 2021, restructuring most of the contracts of their clients. We are likely to see the full Covid19 impact on banks in the FY2021 results. Proactive banks must use data analytics and business intelligence to examine the impact of macro and microeconomic developments on the portfolio to anticipate and manage asset quality.
- High risky lending segments have a high impact on capital adequacy. Banks must implement a sound business model that provides adequate risk management for sustainable growth. Banks that offer high rates of fixed deposits, tend to take high risks in lending which directly affects the asset quality and capital adequacy
- The BOU new capital requirements affect many banks implying that implementation may take longer (3 -5 years) since immediate enforcement by the regulator could adversely affect disrupt the banking industry.
- Due to more regulatory policies aiming at financial deepening and inclusion, we see more mergers and acquisitions in the banking industry in the next 10 years.
- Lending to the private sector yields high interest, high-risk lending exposes bank deposits (liabilities) to the losses, thereby causing banks to experience erosion of their capital reserves. In addition to thorough credit assessment, banks must use data analytics and machine learning models to set credit scores for respective segments based on past performance to minimize risks of default.
- Investment in securities is the best strategy to manage credit risk. Banks like UBA, which had an ever-worsening accumulated losses position, have started to post decent y-o-y profits thanks to increasing investment in securities, which the regulator seems not yet bothered
- High projected valuation is premised on strong bank fundamentals like digital agenda, portfolio mix, the cost to income ratio and jaws ratio, scalable business model and type of customers. A bank with effective digital foundations has more projected agility compared to a bank with a huge non-scalable asset base like real estate and or vehicles which add no value to cost efficiencies and scalability to meet new demand without huge capital outlay pressures.
- Banks with high projected equity will grow revenue faster than they will burn costs, have created deliberate market choices to win and have unique visibility in the market.
- For non-interest income, the aspiration threshold is 40% and must not be below 30%. A large non-interest income threatens to drive clients away from the bank if it is driven by charges and transaction fees, whereas a little one exposes the bank to significant credit risk.
- Banks that grow their interest income over 40% risk losing their concentration as commercial banks and become increasingly involved in investment banking.
- Winning banks, however, grow non-interest incomes from innovative offerings like wealth management, fin-tech incomes driven through enabling payments and the attendant commission shares with the ecosystem partners. These “customer convenience” commission income, if properly optimized transform the bank into a sustainable powerhouse for unprecedented future success.
- Stock market listing is recommended for all banks. It increases the value of the bank as a result of another level of regulatory oversight by the capital markets authority in addition to the Central bank. Listed banks have consistently provided more information about their strategic imperatives, business models, future growth as well as more accountability to the stakeholders
- Each bank needs to monitor the cost of deposits, non-interest income (more specifically non-funded income) contribution to the total revenue and the cost to income ratios, as part of the scorecard. These indicators will help fine-tune the business model, strategic priorities, and digital agenda for sustainable value delivery.
- The high cost of deposits affects bank profitability. Banks must invest in offering an excellent customer experience especially by taking the bank to the customers using convenient, simple and reliable alternative channels. This attracts customers to save with the bank with provides unlimited deposits for lending
- Banks must develop deliberate deposit mobilization strategies as part of their digital agenda. The mobile banking and agency channels, among others, must have customer convenience to deposit at the centre of their innovation
- Pride Microfinance, FINCA, Brac and UGAFODE had the highest net interest margins of 63.87 per cent, 57.49 per cent, 35.23 per cent and 27.02 per cent. This is particularly due to the type of institutions as they target micro borrowers charging interest ranging from 20 to 30 per cent on each loan due to increased risk of borrowers most of which lack collateral. Micro and retail banking present a lot of opportunities to grow as corporate clients tend to be price-sensitive while retail and micro-clients tend to be convenience driven.
- An optimal portfolio mix is key as a risk management strategy. The top banks with the highest net margins have reported adverse asset quality figures. Mixing the portfolio to strike a balance between corporate and micro is key for sustainable growth.
- A focus on deposits growth bank-wide creates a positive impact to grow other areas of the bank since it involves deeper customer relationships and positive brand visibility. To win, banks must put deposit growth as one of the top priorities. Deposits growth from savings and current accounts leads to growth in revenue and assets.
- To grow deposits, winning banks put more focus on convenient banking channels especially internet and mobile, relationship banking (corporate social investment, financial literacy training and customized advice for better personal wealth management) and make loan access very easy and swift for borrowers
- The general industry cash coverage has weakened year on year by two per cent, surprisingly at a time when the economy was shaken. This was particularly caused by an increased focus on securities since they were high yielding, yet loans and advances remained fairly high. It is a high risk for the economy to only hold 19.88 per cent of customer deposits in cash. Banks must embrace data analytics and business intelligence to make data-driven decisions. Developing a data management framework to set a foundation for robust analytics capabilities would be a great starting point.